Australian Internet Loans Business Loan Repayment Calculator
Estimate repayments with our Business Loan Calculator. Compare finance options, tailor loan terms, and plan with confidence for your business growth.
Calculator results are estimates based on inputs and assumptions and are provided for general information only. They are not quotes, offers, approvals, eligibility assessments or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Business Loan Details:
Important!
Business Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Business Loan Amortisation Calculator
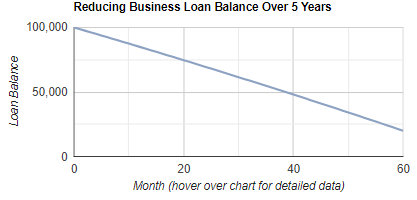
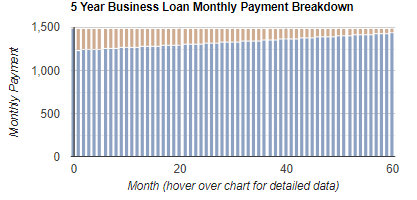
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Business Loan Repayment Calculator
Our Business Loan Repayment Calculator helps you estimate business loan repayments, compare finance options and understand the true cost of borrowing before you commit. It is important because small changes to your loan amount, interest rate, term or balloon payment can materially change cash flow, total interest and end-of-term obligations. This calculator provides an indicative estimate only and is designed to support planning and budgeting for business growth.
How to complete each section for the best result:
1. Loan Amount
Enter the amount you expect to borrow as a whole number (no dots or commas). Include any costs you plan to capitalise into the loan, such as stamp duty, registration, insurance or other applicable fees, so the estimate reflects your real financed amount.
2. Balloon or Residual Payment (optional)
Select a residual as a percentage of the purchase price. A higher residual usually reduces ongoing repayments, but increases the amount due at the end and can increase total interest over the term. Choose a residual only if you have a realistic plan to refinance, pay it out, or sell an asset to meet the final amount.
3. Term of Loan
Select the number of years you want to repay the loan. A longer term generally lowers periodic repayments but increases total interest paid. A shorter term can reduce total cost but may place pressure on cash flow.
4. Interest Rate
Select an indicative annual interest rate to run a scenario. Your actual rate depends on lender assessment and your business circumstances, so consider testing multiple rates to stress-test affordability.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a budgeting guide for regular cash flow planning. If you selected a residual, remember the final payout is additional to the periodic repayments.
2. Amortisation charts
Review the reducing loan balance over time and the split between interest and principal. Early repayments typically include a higher interest component, with principal reduction accelerating later.
General information only, not personal financial advice. It does not consider your objectives, financial situation or needs. Consider the loan contract, fees, repayment frequency, and whether the repayments remain affordable under higher rates or lower revenue, and seek professional advice if required.
Recent vehicle finance commentary has put balloon and residual payments back in the spotlight, particularly for Australians considering cars, utes, vans, trucks or business equipment. The issue is not that balloon structures are inherently unsuitable. Used carefully, they can help borrowers manage cash flow by lowering regular repayments. The risk is that the smaller monthly figure can distract from the larger amount still payable at the end of the loan or lease term. - read more
Recent lending market coverage points to a more competitive spring for Australian borrowers, with some banks and non-bank lenders adjusting selected fixed and variable loan offers. The shift does not mean borrowing has suddenly become easy or cheap, but it does suggest lenders are again competing harder for well-prepared applicants with stable income, clean repayment histories and clear loan purposes. - read more
Recent small business lending commentary points to a continuing change in how Australian lenders are assessing finance requests: the focus is moving beyond annual accounts and into the day-to-day health of cash flow. For business owners seeking working capital, vehicle finance, equipment upgrades or short-term funding, that means bank statements, tax position and repayment conduct are becoming central to the conversation. - read more
Creditworthiness represents a cornerstone in the world of finance, serving as the gauge by which lenders assess an individual's reliability in repaying debt. It's this measurement that can open doors to various financing opportunities or, conversely, become a barrier to accessing essential credit lines. So, what is creditworthiness, and why does it matter? - read more
Online loans have revolutionized the way Australians access finance. With the emergence of fintech and the convenience of the internet, obtaining a loan is now faster, easier, and often more customer-centric. When managed responsibly, the online loan application process empowers borrowers with quick funds for life's unexpected expenses or investments. However, the speed and simplicity of online transactions can also lead to common oversights. - read more
Personal loans in Australia can be used for purposes such as consolidating debt, funding major purchases or covering unexpected costs. One of the key choices when comparing loans is whether to choose a fixed interest rate or a variable interest rate. - read more